Summary & Key Takeaway:
In Texas, sudden and accidental internal plumbing failures like burst pipes and water heater ruptures are covered by standard homeowners insurance (HO-3), not flood insurance. Overland storm surges and rising bayou floodwaters require a separate FEMA NFIP flood insurance policy.
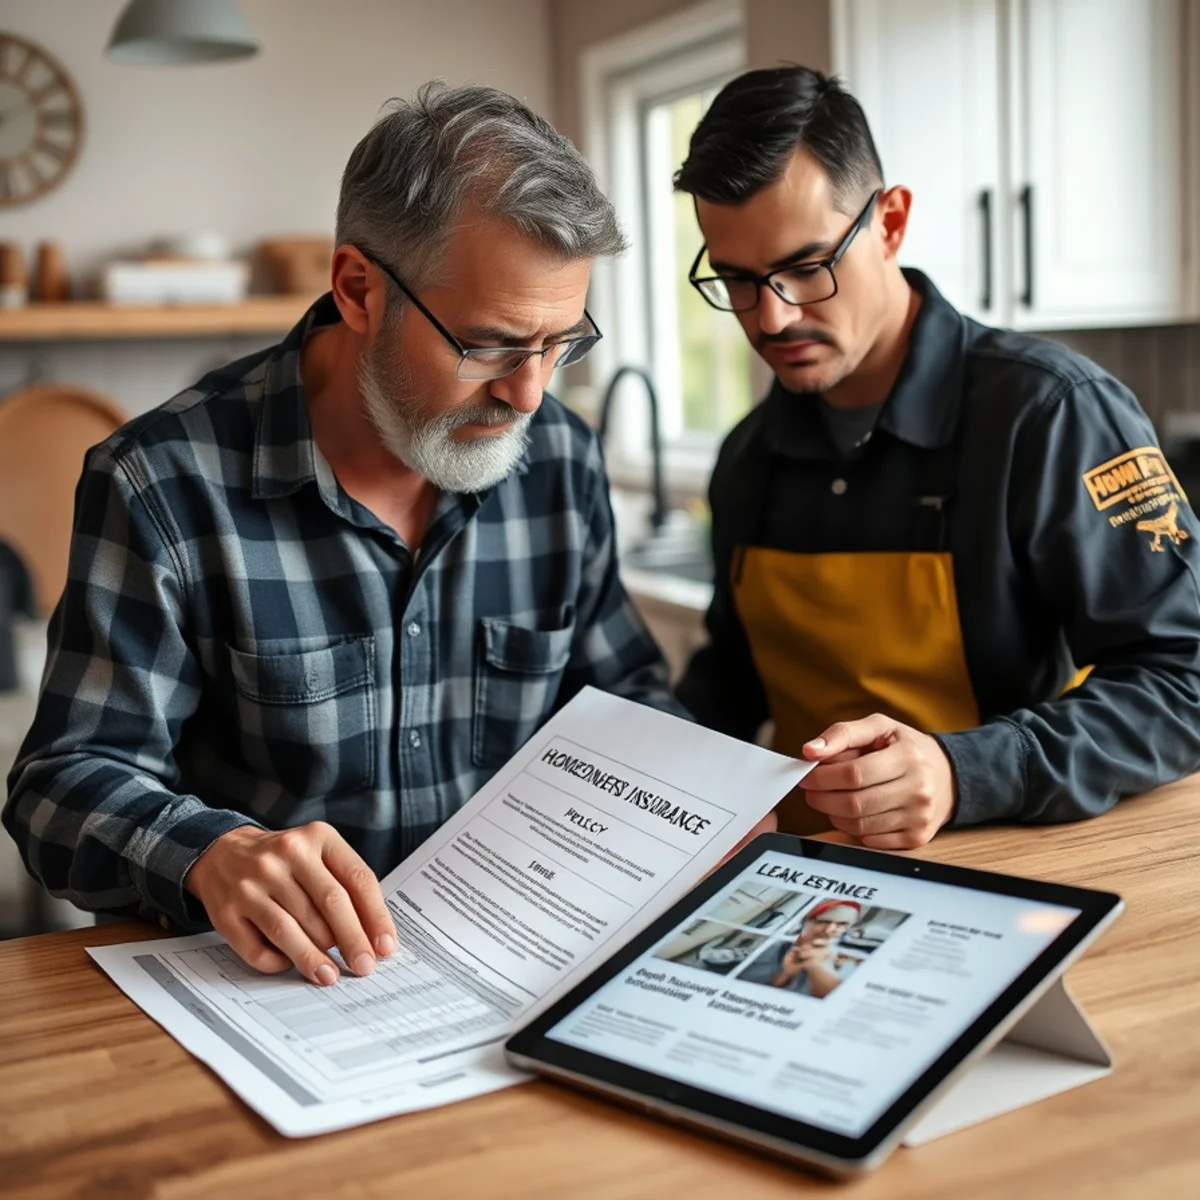
One of the most frequent points of confusion for League City homeowners facing water in their home is whether to file a claim under their standard homeowners insurance policy or their FEMA flood insurance policy. Many assume that any water on the floor constitutes a 'flood.' In the eyes of Texas insurance law and the Texas Department of Insurance (TDI), however, internal plumbing failures and overland natural flooding are treated as two entirely separate legal categories.
The Golden Rule: Top-Down vs. Ground-Up Water
A helpful rule of thumb for Texas property owners is the distinction between 'top-down' plumbing water and 'ground-up' environmental floodwater:
- Homeowners Insurance (HO-3/HO-B): Covers sudden and accidental internal discharge of water from plumbing, heating, or air conditioning systems. If an attic copper pipe freezes, a braided supply line snaps under a sink, or an under-slab pipe ruptures, your homeowners insurance covers the resulting structural damage and water extraction.
- FEMA Flood Insurance (NFIP): Covers water that touches the ground outside your home first before entering across thresholds. This includes rising bayou floodwaters from Clear Creek, storm surges from Galveston Bay, and street water overflow during tropical storms. Flood policies never cover internal plumbing pipe bursts.
Insurance Coverage Comparison Matrix
| Plumbing Failure Event | Covered Policy | Typical Deductible | What Is Paid Out |
|---|---|---|---|
| Attic Freeze Burst Pipe | Homeowners (HO-3) | Standard Property ($1,000–$2,500) | Drywall, flooring, drying, tear-out; pipe repair out-of-pocket |
| Slab Foundation Copper Leak | Homeowners (Tear-Out Rider) | Standard Property Deductible | Access/tear-out & water damage covered; pipe patch excluded |
| Sewer Backup From Street | Optional Sewer Rider Only | Separate Endorsement ($500) | Full biohazard extraction & flooring if endorsement was purchased |
| Clear Creek Rising Flood Surge | FEMA NFIP Flood Policy | Separate Flood Deductible | Structural drywall, appliances, subflooring up to policy limits |
The Critical 'Tear-Out' Clause for Slab Leaks
For League City homeowners experiencing a foundation slab leak, understanding the 'tear-out' provision in your policy is critical. In Texas, most standard homeowners policies cover the cost of tearing out concrete or accessing the pipe beneath the slab, as well as repairing the water damage to baseboards and flooring. However, the physical plumbing repair itself (the few inches of copper replacement or PEX bypass) is considered regular home maintenance and is typically an out-of-pocket cost of $500 to $1,500.
Expert E-E-A-T Advice: How to Document Your Claim Flawlessly
Insurance companies look for reasons to deny claims based on 'gradual, ongoing leakage' or 'deferred maintenance.' To protect your claim:
- Never admit to an adjuster that a pipe has been 'leaking for weeks.' A burst pipe is sudden and accidental.
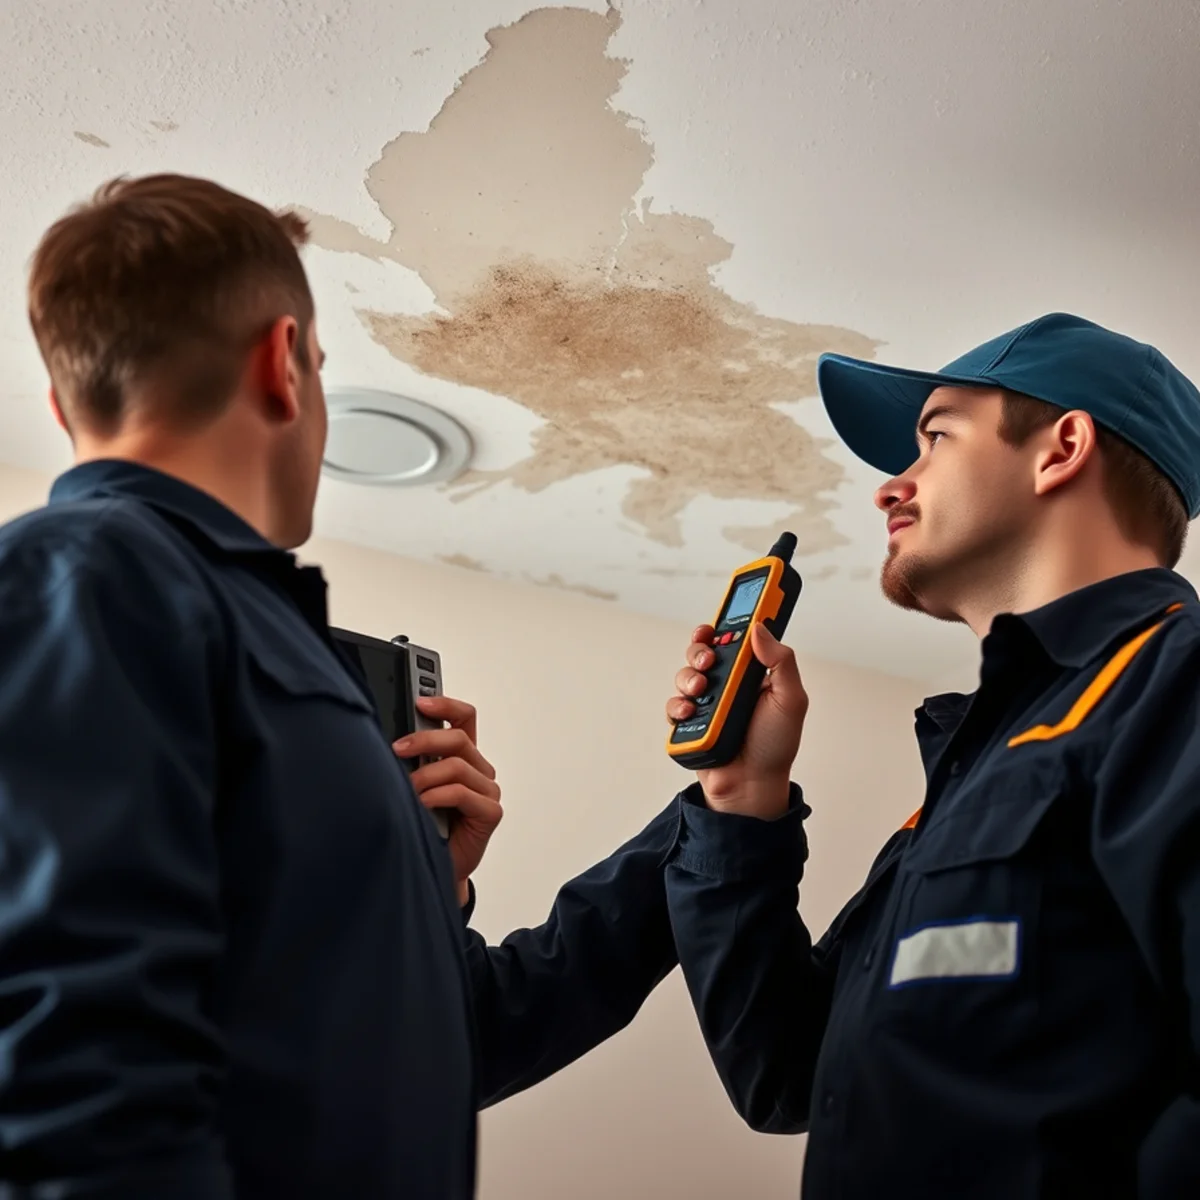
- Have our licensed Texas Master Plumber provide a formal diagnostic report identifying the specific failure mechanism (e.g., sudden water hammer shear or freeze rupture).
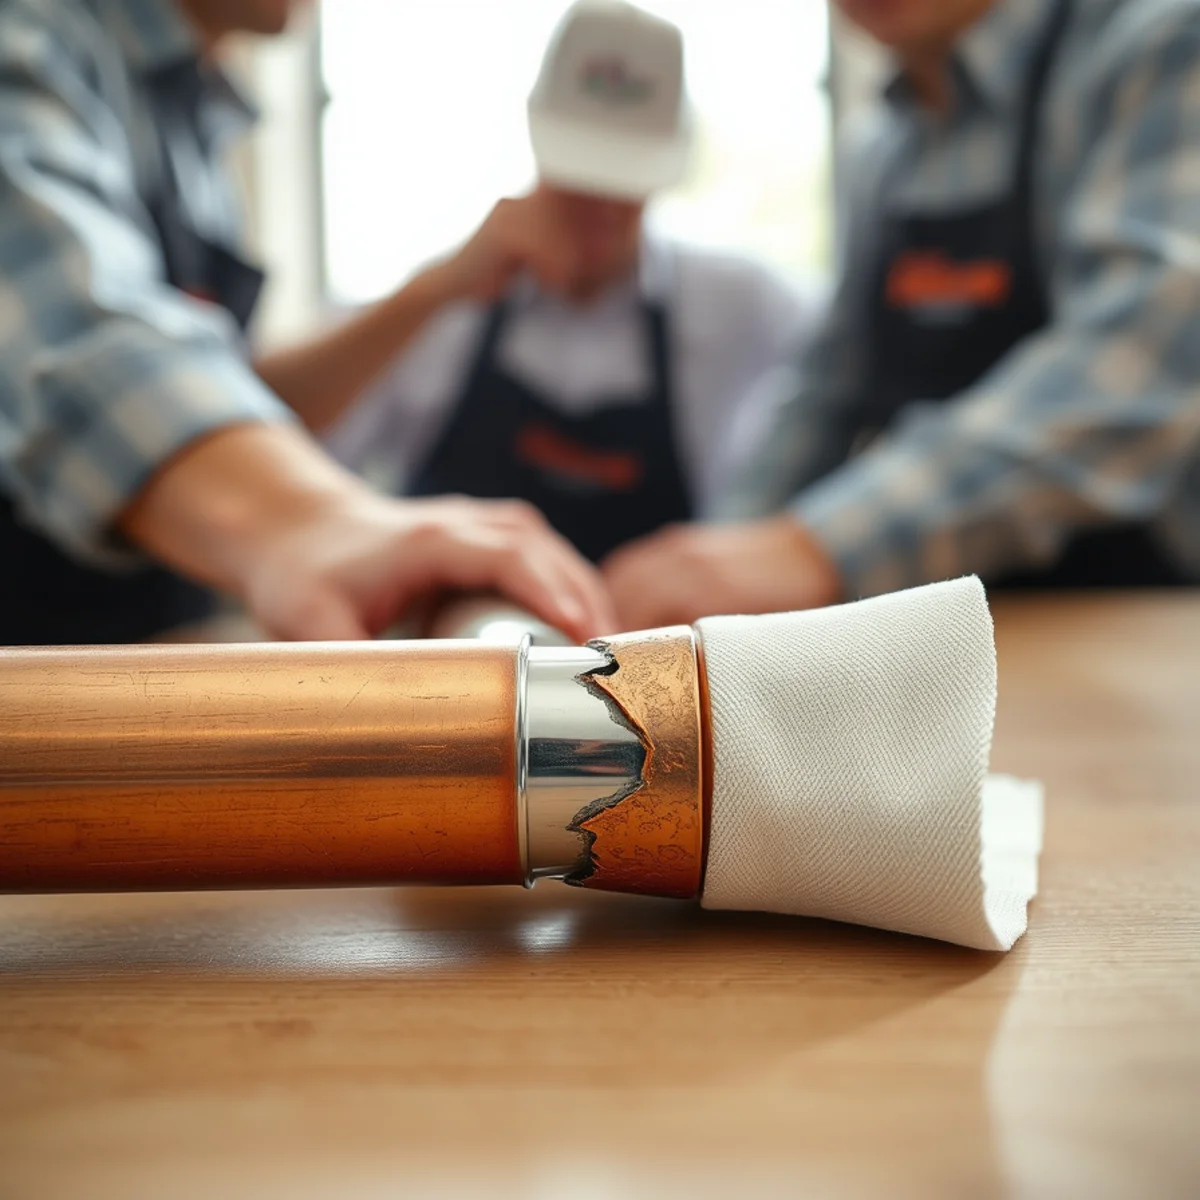
- Save the failed copper fitting or ruptured braided supply hose in a plastic bag as physical evidence.
If you need immediate emergency repair and insurance documentation in League City, Clear Lake Shores, TX, or Galveston County, contact League City Pro Plumbing & Drain at (831) 290-4327 for Burst Pipe Repair and professional insurance reporting.
Illustrated Field Diagnostics & Procedure Steps
This guide was compiled by licensed Texas Master Plumbers with over 15 years of active field diagnostic experience across League City, Clear Lake, and Galveston County. Every diagnostic protocol, code citation, and repair recommendation adheres strictly to the 2021 International Plumbing Code (IPC) and municipal guidelines. For emergency triage or on-site inspections, our mobile fleet is dispatched 24/7 from 1930 Highway 3 S.
Related Plumbing Services:
Areas Mentioned in this Guide:
Questions Answered in this Guide
Frequently asked questions related to this plumbing topic.
Generally, no. Homeowners insurance covers the consequential water damage (floors, sheetrock, ceilings, drying) and the tear-out costs to reach the pipe, while the physical plumbing repair is usually the owner's responsibility.